What's in your free Game Plan
Built from your 6 answers, on your screen as soon as you finish.
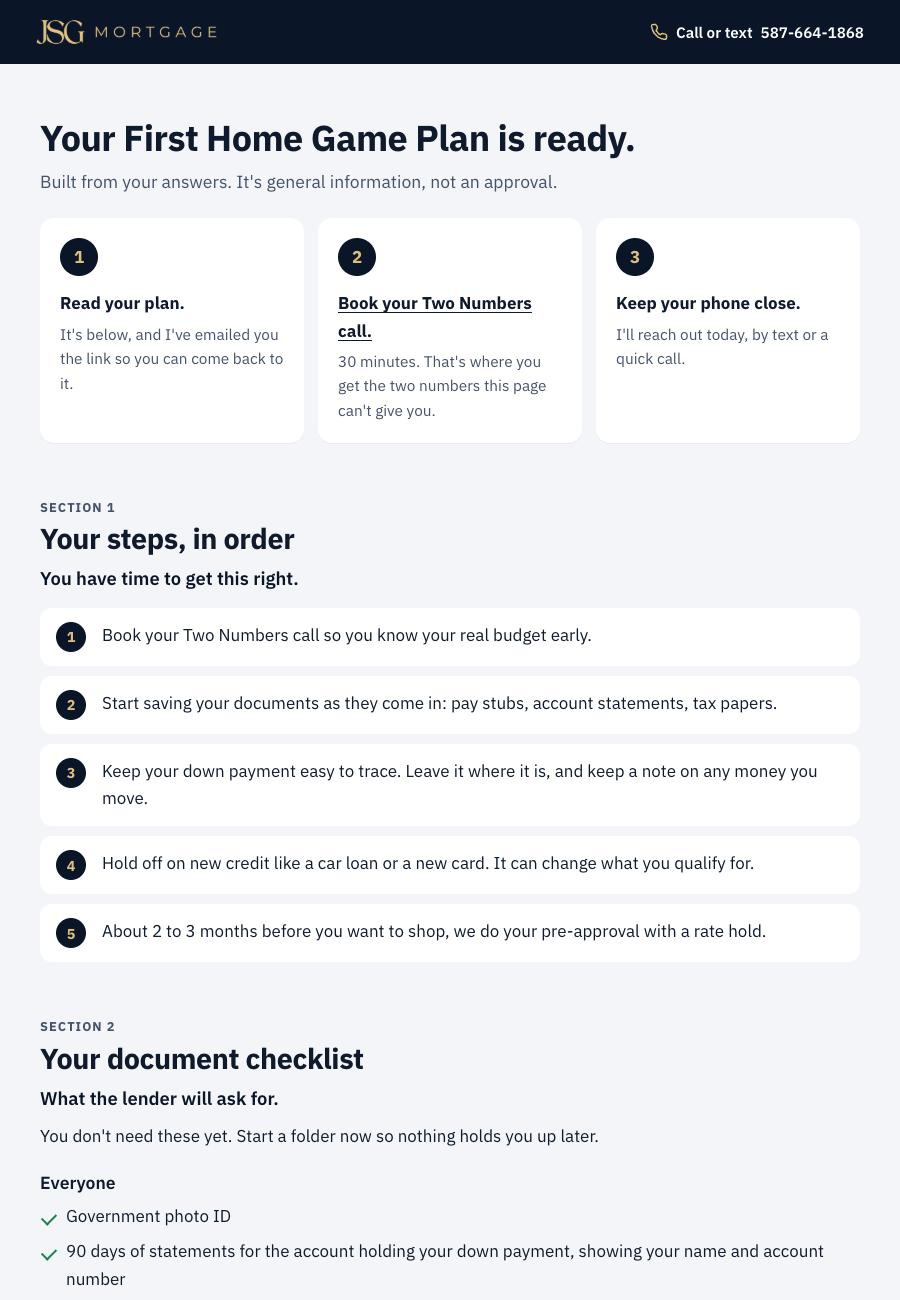
- Your steps, in order. What to do first for your timeline, whether you're buying in 3 months or not sure yet.
- Your document checklist. Exactly what a lender will ask for, based on how you earn your income.
- The cash you'll need. Down payment and closing costs, so there are no surprises on closing day.
- First-time buyer programs. The ones that could apply to you.
- How to get your two numbers. Your comfort number and your maximum, on a free 30-minute call.
How I get first-time buyers to the keys
Three steps. You always know which one you're on, and what's next.
- 1. Two numbers
First I ask what monthly payment you'd be comfortable with. That gives us your comfort number. Then I work out your maximum, what a lender could approve. You see both side by side, with every cost listed.
- 2. File check
I go through your T4s, notices of assessment, pay stubs and statements as if you've already found the house. You hear about problems now, before you've fallen for a place.
- 3. Rate hold
You get pre-approved with a rate hold. Most lenders hold your rate for up to 120 days while you look. You're not locked into buying anything, and you do the paperwork from your phone.
Say you make $85,000 a year, with a $400 car payment.
A home around $270,000
A home around $350,000
About $80,000 more house costs about $500 more a month. Maybe that's worth it to you, maybe it isn't. It's your call. You'll have every number in front of you.
Example only. Not an approval. Rates change.
Hi, I'm Japnam. So what's the catch?
On a normal purchase, you don't pay me. The lender does. If your file ever needed a lender where a fee applies, you'd know the amount before you signed anything.
I'm a mortgage associate in Calgary and I don't work for one bank. I grew up around real estate and shot listing photos for realtors all over the city. Now I work on mortgage files every day, on a team with two senior brokers who look at your file before the big steps.
Everything is checked more than once before it goes to a lender. And I'll always explain the trade-offs in plain English before you sign anything.
Mortgage Associate · Indi Mortgage
Questions first-time buyers ask me
Does this check my credit?
No. Answering these questions doesn't touch your credit. A credit check only happens later, with your written consent, if you decide to apply.
What does it cost?
Your Game Plan is free. For most purchases, the lender pays the brokerage. If your file ever needs a lender where a fee applies, you'll know before anything is signed.
Why not just go to my bank?
Your bank might be the right answer. But a bank can only show you its own products and its own rules, and if it's your first time, you have nothing to compare it to. If your bank's offer is the best one for you, I'll tell you.
I'm not ready yet. Is this too early?
Early is the best time. If you wait until you've found a home, you find out about problems at the worst possible moment. Checking now gives you time to fix things, and you walk away with a plan either way.
Who will contact me, and how?
Me, Japnam. I'll reach out personally by text, email or a quick call. No call centre, no spam. You're under no obligation to use me.
Get your Game Plan in about a minute
You can close this page, and nothing bad happens today. But six months from now, you could be asking the same questions and still paying rent. Or you can take a minute and find out.
Get my free Game Plan6 quick questions. No credit check, no documents, no obligation.
I can't promise you the lowest rate or an approval. What I can promise is a clear process, and that you'll understand every choice before you sign.